Disclosure: This is my own book, written and sold by me. When you buy through a link on this page, you are buying directly from the author.
After my divorce, my credit was destroyed. Bills, financial disruption, and the pressure of starting over left me wondering whether buying a home would ever be possible. I did not have a credit repair company handling the work for me. I had to learn how the credit and mortgage process worked, make a realistic plan, and rebuild my financial position myself.
I am Theo, a U.S. Army veteran who served for 10 years. Military service taught me the value of discipline, preparation, and following a plan, but rebuilding after a divorce was still difficult. It required patience and a willingness to face financial problems instead of avoiding them.
Over time, I rebuilt my credit, learned how to prepare for a mortgage, and purchased my home. My credit score is now 771. That is my personal result, not a promise of what anyone else will achieve. Every credit profile, income situation, lender, and homebuying journey is different.
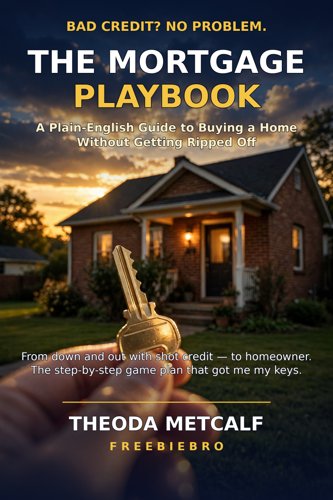
I created The Mortgage Playbook to organize what I learned into a practical resource for people who want to rebuild credit to buy a home. The book costs $27 and explains the complete method in one place without requiring readers to begin with advanced financial knowledge.
Why I Decided to Rebuild My Credit Myself
When my credit was at its worst, it would have been easy to believe that someone else had to fix everything for me. I quickly realized that I needed to understand my own financial situation, even if I eventually chose to ask a lender, housing counselor, attorney, or other qualified professional for help.
I wanted to know what was affecting my credit, what mortgage lenders generally review, and how my financial decisions connected to my goal of buying a home. Learning those connections helped me move forward with more confidence.
Doing the work myself did not mean looking for shortcuts. It meant accepting responsibility, becoming organized, and making decisions based on my actual circumstances. It also meant understanding that progress would take time.
What Rebuilding After Divorce Taught Me
Credit problems can feel personal, but they are still problems to solve
A damaged credit profile can carry a lot of shame. Divorce can make those feelings even heavier because financial accounts, living expenses, and responsibilities may change quickly.
I learned to separate my identity from the numbers. My credit situation was serious, but it did not define my value or determine my entire future. Treating it as a practical problem helped me focus on what I could control.
Homeownership requires more than watching a score
A credit score matters, but it is not the only part of mortgage readiness. Depending on the loan and lender, factors may include income, employment, debt, available funds, payment history, documentation, and the type of property being purchased.
That is why my goal was not simply to chase a number. I wanted to become a more informed and prepared mortgage applicant. A higher score without a workable budget or complete documentation would not have addressed the entire homebuying picture.
Consistency mattered more than excitement
Financial improvement can feel slow. There may not be a dramatic change every week or month. I had to stay focused on the long-term objective instead of expecting instant results.
No book, company, or individual can guarantee a particular credit score or mortgage approval. What a useful resource can do is help someone understand the process, identify relevant questions, and approach decisions with a clearer plan.
Practical Ways to Prepare for the Homebuying Journey
The detailed credit rebuilding method I used is inside The Mortgage Playbook. I am intentionally not reproducing that step-by-step system here. However, there are several practical ways beginners can prepare before or while working through the book.
Define what buying a home means for you
Start by making the goal specific. Consider where you want to live, what kind of property may fit your needs, and what monthly housing expense could be manageable. This is not about choosing a dream listing immediately. It is about connecting homeownership to your real life.
For example, a self-employed online business owner might need space for a home office but may prefer a smaller property with lower ongoing expenses. A veteran with a family may care more about school districts, commuting distance, or room to grow. Different priorities lead to different budgets and timelines.
Build a realistic housing budget
A mortgage payment is only part of homeownership. A useful budget may also account for property taxes, homeowners insurance, utilities, maintenance, possible association fees, moving expenses, and repairs.
Consider a hypothetical buyer who can handle a proposed mortgage payment but has no room left for an unexpected plumbing repair. That buyer may decide to target a lower price range or spend more time building financial reserves. The right choice depends on the person’s circumstances.
Organize your financial paperwork
Mortgage applications can involve significant documentation. Keeping records organized can make conversations with lenders less stressful. Depending on your employment and financial situation, requested documents may include identification, income records, tax documents, bank statements, information about debts, or explanations of certain account activity.
Self-employed people may face different documentation requirements from traditional employees. Veterans may also want to gather relevant service or eligibility records if they plan to explore a VA-backed loan. A qualified lender can explain what is required for a particular loan program.
Learn the basic mortgage vocabulary
Terms such as prequalification, preapproval, principal, interest, escrow, closing costs, debt-to-income ratio, and loan estimate can be confusing at first. Learning the vocabulary makes it easier to ask useful questions and compare options.
You do not need to become a mortgage professional. You do need enough understanding to recognize when you need clarification. Never be afraid to ask a lender to explain a fee, requirement, or document in plain language.
Avoid making major decisions without understanding the impact
When preparing for a mortgage, seemingly unrelated financial choices may affect an application. Before taking on a major new obligation, moving money between accounts, changing employment, or making another substantial financial decision, consider discussing the possible impact with a qualified mortgage professional.
This is especially important because lending standards vary. Advice that fits one borrower may not fit another.
Compare professionals as carefully as you compare homes
A lender, broker, real estate agent, housing counselor, attorney, or tax professional may play a role in the process. Ask about experience, fees, communication, and the options available to you.
One lender’s answer may not represent every possible program, but that does not mean every borrower will qualify elsewhere. Comparing legitimate options can help you make an informed decision without assuming approval is guaranteed.
What Is Inside The Mortgage Playbook?
The Mortgage Playbook is the resource I created from my experience rebuilding after divorce and preparing to purchase my home. It is written for beginners who want a clearer view of the credit and mortgage journey.
The book covers the framework I used to understand my credit situation, organize the rebuilding process, and connect that work to mortgage preparation. It also addresses the mindset and planning needed to keep moving when progress feels slow.
Readers will learn about the areas that deserve attention when credit has been damaged, how credit rebuilding relates to mortgage readiness, and what to consider while preparing for lender conversations. The actual step-by-step credit repair method remains inside the book.
The goal is not to sell a magical score increase or an instant path to approval. The goal is to provide a structured playbook that can help readers become more informed, organized, and prepared.
Who The Mortgage Playbook Can Help
The book may be useful if you:
- Have damaged credit and want to work toward homeownership.
- Are recovering financially after divorce, job loss, or another major life change.
- Feel overwhelmed by credit and mortgage terminology.
- Want to understand your own situation instead of depending entirely on a credit repair company.
- Are a veteran or first-time buyer beginning to explore mortgage options.
- Own a small business or earn self-employment income and want to prepare more carefully.
- Need a structured resource to help you stay focused on a long-term housing goal.
The book is educational and does not replace personalized legal, tax, credit, or mortgage advice. It also cannot guarantee a specific credit score, loan approval, interest rate, or home purchase. Your outcome will depend on your starting point, actions, finances, lender requirements, and other individual factors.
Why I Priced the Book at $27
I wanted The Mortgage Playbook to be reasonably accessible for people who are trying to improve their financial position. The $27 price gives readers the complete resource without requiring an ongoing subscription or a high-cost service.
It is still important to decide whether the book fits your needs and budget. If you are not ready to purchase, you can begin by organizing your goals, listing your questions, and speaking with reputable professionals. If you want the complete system I put together, the book contains the method in a structured format.
My Perspective as a Veteran and Homeowner
My 10 years in the U.S. Army taught me that a playbook only works when it is paired with consistent action. The same principle applied when I needed to rebuild credit to buy a home.
I could not change the fact that my divorce had happened or that my credit had been damaged. I could decide how I responded. I learned, organized my finances, followed a plan, and stayed focused on the larger goal.
Buying my home was meaningful because I understood what it took for me to reach that point. My credit score is now 771, but I share that number only as part of my story. It should not be treated as a prediction or guarantee for anyone else.
Conclusion: Start With a Clear Plan
If your credit has been damaged, homeownership may feel far away. That does not mean you should ignore the goal or rush into a questionable promise. Start by understanding where you stand, creating a realistic housing objective, organizing your information, and learning how the mortgage process works.
I wrote The Mortgage Playbook because I know what it feels like to start over. This post includes a link to my own book, so I may benefit when you purchase it. My intention is to offer the structured resource I wish I had when I began rebuilding.
Frequently Asked Questions
Can The Mortgage Playbook guarantee that my credit score will improve?
No. The book does not guarantee a particular score, timeline, mortgage approval, interest rate, or result. Credit outcomes depend on each person’s financial history, starting point, decisions, and other factors.
Do I need to hire a credit repair company?
I rebuilt my credit myself without using a company, but everyone should choose an approach that fits their circumstances. The book explains the method I used so readers can become more informed. Complex legal or financial situations may require help from an appropriate qualified professional.
Is the book only for veterans?
No. I am a U.S. Army veteran, and that experience shaped my approach, but the book is designed for veterans and civilians alike. It can help beginners, first-time buyers, people recovering from divorce, and small business owners preparing for homeownership.
Does a 771 credit score mean everyone can get the same result?
No. My credit score is now 771, but that is my personal outcome. I do not promise that another reader will reach the same score or receive mortgage approval.
Where can I get The Mortgage Playbook?
The Mortgage Playbook costs $27. If you are ready to learn the complete method I used and build a more organized plan for your own mortgage journey, get The Mortgage Playbook here.
Next step: If collections are what is dragging your score down, read how I handled mine in Credit Repair Strategies Revealed. And before you spend a dime, grab my free credit tools here: freebiebrovault.com/start
How I rebuilt my credit and bought my home — the exact steps, in plain English.
GET IT — $27